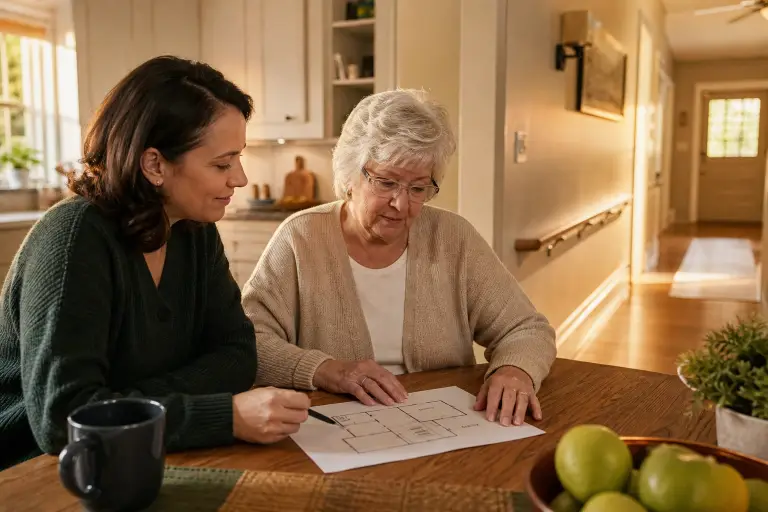
Arranging home care for the first time can feel less like running an errand and more like managing a small project. You’re likely to get steadier results when you pin down daily needs, likely costs, and family availability before choosing a provider.
Start With What Daily Life Actually Requires
Before calling anyone, spend a few days observing how your family member moves through a normal day. The goal isn’t to diagnose a condition. You’re simply recording where help is needed in clear terms so you can ask providers for the right support.
Clinicians use two lists for this, and they’re useful for families as well. The first is Activities of Daily Living, usually called ADLs.
The Katz Index groups them as bathing and dressing, toileting and transferring, continence and feeding. Walk through each area and note what currently happens, including any help already provided by relatives.
Consider whether your dad can get in and out of the shower safely on his own. Note whether your mom needs hands-on help to stand from a chair or reach the bathroom at night.
The second list is Instrumental Activities of Daily Living, or IADLs. These cover medication management, meal preparation, transportation, and housework. Such tasks tend to slip first, and they’re often what prompts the initial family conversation about care.
You might notice missed doses or a fridge full of expired food. There may be unopened mail and a new reluctance to drive after dark.
Write down both sets of needs and keep the wording concrete. Include notes about morning routines, evening habits, sleep patterns, and any history of falls.
If siblings are involved, ask each person to add what they’ve observed. Talk directly with your family member about health needs and sources of daily frustration, then ask what type of help would feel comfortable.
Learn the difference between skilled care and custodial care
Many families get tripped up by this distinction, and the misunderstanding can be expensive. Skilled nursing care is medical care ordered by a doctor and delivered by a nurse. Examples include wound care, injections, post-surgery checks, and lab draws.
Most of what families call home care is custodial or personal care. It includes help with bathing and dressing, along with mobility support and companionship.
This type of assistance can allow someone to remain safely at home when everyday tasks become difficult.
The Medicare home health benefit has specific eligibility and coverage rules, including requirements related to being homebound and needing part-time or intermittent skilled services.
Covered home health aide care may be available in limited circumstances alongside skilled care, but Medicare does not pay for 24-hour home care or personal care when that is the only need. Confirm current coverage directly with Medicare or the relevant plan.
Don’t make that assumption.
If your family member needs both medical tasks and daily support, you’ll probably need two separate arrangements.
Skilled visits might come through a certified home health provider for a limited period. Daily support will generally be private pay or covered through one of the other programs discussed below.
Ask each agency up front which type of care it handles. From day one, you need a clear explanation of what counts as skilled care, what counts as custodial care, and who pays for each service.
Talk About Money Before You Fall in Love with a Plan
Many families pay some or all non-medical home care costs privately, so work through the numbers early. Decide how many hours per week are genuinely needed, then compare that figure with your budget and your family’s availability. The answer will shape every other choice, whether that means part-time morning assistance or full live-in coverage.
The national median cost of a home health aide is roughly $33 per hour, which comes to about $75,000 per year when care is needed 44 hours a week (Genworth Cost of Care Survey).
Treat that figure as a starting point for your calculations rather than a quote. Rates vary by location and shift length.
Once you have a weekly estimate, review possible funding sources in order. Begin with long-term care insurance if a policy exists. Don’t assume the policy will reimburse you. Read its benefit triggers carefully and check the elimination period before arranging services.
Note the daily cap and lifetime maximum as well. Call the carrier with the policy in hand, then ask what documentation is required for a claim.
Next, investigate veterans benefits if your family member or a spouse served. Aid and Attendance can help eligible people with care costs, but the paperwork takes time. Start early if this option may apply.
You should also ask about Medicaid Home and Community Based Services waivers. These waivers are the main route to publicly funded help at home for people who meet income and asset rules.
Requirements vary by program, so speak with a local benefits counselor before moving money around. Many families combine at least two sources. Private funds, for example, might cover the first few months while other approvals are pending.
Another option is to combine family coverage on weekends with paid support during the week. Put the arrangement in writing so every sibling sees the same costs and responsibilities.
A short family meeting based on real numbers is far more useful than months of vague anxiety about money.
Vet providers on Reliability, not just Price
Price matters, but reliability determines whether the scheduled care actually happens. Home care has high turnover across the industry, so your vetting should cover what happens when a regular caregiver becomes ill or leaves. The answer is often more revealing than a small difference in the hourly rate.
Compare agency services with direct hiring before deciding. Ask an agency whether caregivers are employees or contractors, what screening it completes and how it handles backup coverage.
A household hiring a worker directly may take on payroll, tax, insurance and screening responsibilities, depending on the arrangement and applicable law. Get qualified local advice rather than assuming a worker is an independent contractor.
When interviewing agencies, use the same operational questions each time. Ask how caregivers are screened and whether national background checks are conducted.
Find out the agency’s turnover rate and how long caregivers typically stay. Ask what happens when your assigned caregiver calls off, how quickly backup can arrive, and whom you should contact during an after-hours emergency.
Listen for concrete answers rather than general reassurances. You need names, timelines, and a clear on-call process, together with proof of licensing and insurance where required. Ask for two recent references from families whose health needs are similar to yours.
Scale may affect how an agency organises services. When considering a home care agency with offices in several cities, ask whether training, records and backup staffing are coordinated across locations. If your family member may relocate or divide time between residences, confirm in writing whether and how care can transfer.
If relatives are spread across different locations, consider working with a geriatric care manager. An independent professional may be able to assess care needs and help relatives compare options. Hiring one is not required, so check credentials, fees and provider affiliations before deciding.
Red Flags That Should Make You Keep Looking
Be cautious if an agency cannot explain its backup plan or refuses to provide rates in a written quote. Reputable agencies expect close review and should be willing to answer your questions.
Avoid signing up for large blocks of hours before you have met a caregiver.
Get a Written Care Plan After the in-Home Assessment
Don’t agree to ongoing care without an in-home evaluation. Many agencies offer an assessment through a nurse or supervisor, although the process and any fee vary. The assessor watches how your family member moves and communicates, checks the bathroom and kitchen for fall risks, and asks about medication and meals.
You should attend the assessment. Walk the assessor through the ADL and IADL notes you prepared, including what concerns you during the day and at night. Ask what level of help is recommended and why, then request that the outcome be documented in writing.
The next step is the written care plan, which serves as the operating document for daily support. It should name the assigned caregivers, list the weekly hours, and describe each task by time of day. Preferences involving food and routines should also appear in the plan. If an agency cannot provide this document, look elsewhere.
Insist on practical details. The plan should identify who helps with showers and when, as well as who prepares meals and which foods are acceptable. It should explain who handles medication reminders and how missed doses are recorded.
Responsibility for laundry and light housework should also be clear. A good plan answers these questions without repeated follow-up calls.
If possible, begin with a two-to-four-week trial and use that period to assess the fit. Caregiver compatibility can strongly affect whether the arrangement feels workable from day to day.
Schedule a formal family review before the trial ends, using both the caregiver’s notes and your own observations. Adjust hours or duties while the arrangement is still flexible.
Handle Paperwork and set up the Home Before the First Shift
Ask what privacy authorisation is needed before care begins so the agency can share appropriate updates with designated relatives. Privacy rules and the person’s wishes determine what staff may disclose. Pair it with a health care power of attorney and keep copies somewhere every decision-maker can access.
Respite care is short-term support provided in hourly or overnight blocks, giving a family caregiver a planned break. Many families use it as a first step when they aren’t ready to commit to a weekly schedule.
Family care often involves long hours without days off, and that pace can break down quickly without relief. Outside assistance can make family care sustainable for longer.
Prepare the home with a few simple changes. Clear paths to the bed and bathroom, then install night-lights where feet will land. Place medication lists and key contacts on the fridge.
Decide where caregivers should park and which entrance they should use. Agree on a method for sharing daily notes about meals and mood.
Review on a Schedule and Know When to Adjust
Request brief weekly updates from the agency. Find out what went well, what was missed, and whether the scheduled hours still fit your family member’s needs.
Arrange a full care plan reassessment every 60 to 90 days, or sooner following a hospital stay or an obvious change in mobility.
How to Handle a Mismatch
Fit problems are common, and most can be addressed. If personalities clash, tell the agency early and provide specific details. Good agencies will arrange a fast rematch without unnecessary conflict. Don’t wait for months before raising the issue.
A sound start to home care depends on a few consistent habits. Understand what help is needed, be realistic about cost, and choose reliability over sales talk. Put the plan in writing and review it regularly. Those steps can make the first month more manageable for everyone in the family.